Renovation Loans in Utah
Finance a home and the improvements it needs in one transaction. Understand how renovation programs like FHA 203(k) and HomeStyle work, and whether one fits your project before you apply.
What a Renovation Loan Means Here
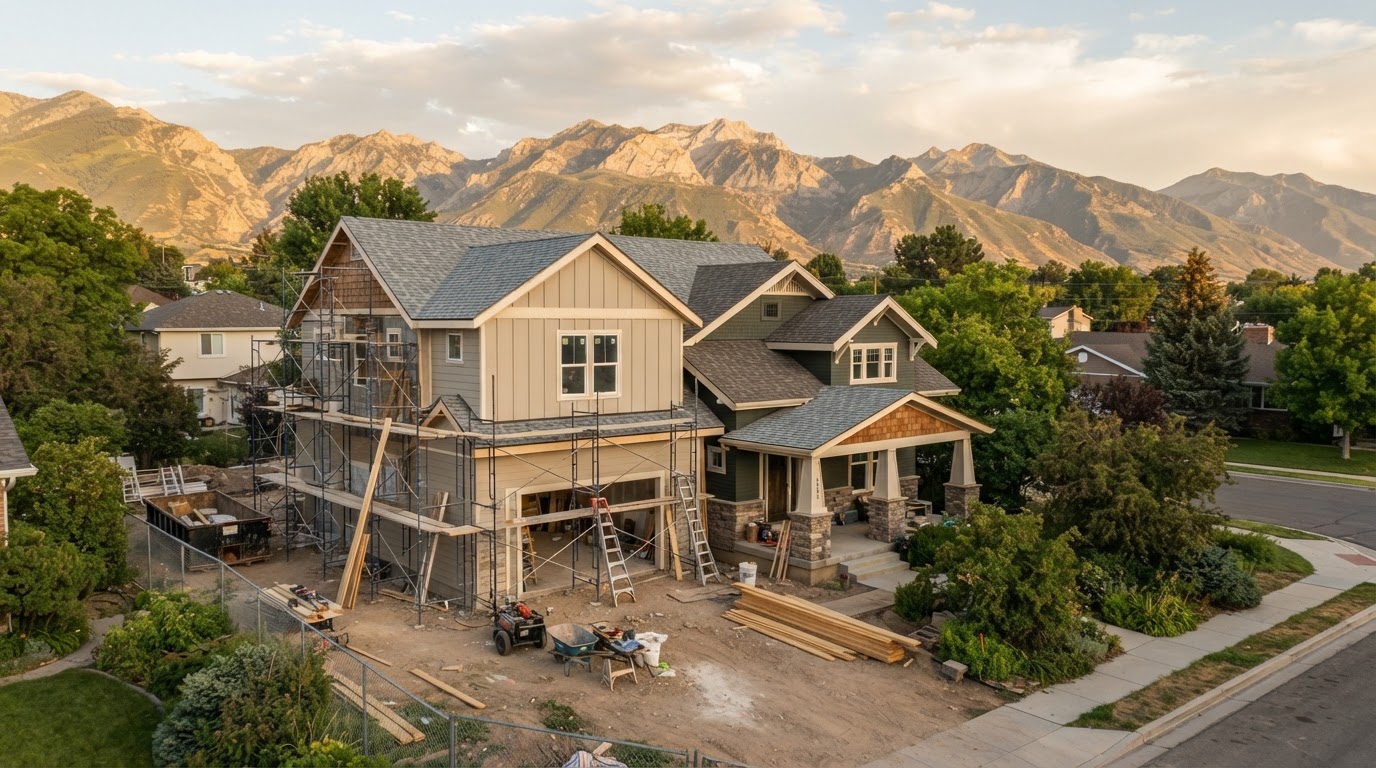
A renovation loan is a mortgage that combines eligible purchase or refinance financing with the cost of approved home improvements into one financing structure. Instead of a separate construction loan or paying for repairs out of pocket, eligible improvement costs are folded into the mortgage based on the home's expected value after the work is completed.
Through Coast2Coast Mortgage, Victor compares eligible renovation programs, including FHA 203(k) and HomeStyle where available, across available wholesale lenders so you understand how each program handles improvements before you decide.
What Renovation Financing May Cover
Eligible improvements depend on the program. Here are the kinds of projects renovation programs are commonly used for. Whether a specific project qualifies depends on the program's rules and your situation.
Mechanical and system updates
Eligible repairs to plumbing, electrical, HVAC, roofing, and other major systems that bring a home up to current standards.
Health and safety repairs
Improvements that address structural, safety, or code-related issues a home may need before it is fully livable.
Cosmetic and finish updates
Some programs may also allow eligible cosmetic work such as flooring, paint, cabinets, and finish updates, depending on the program.
Additions and modifications
Certain programs may allow eligible additions or layout changes, subject to the program's scope rules and project requirements.
FHA 203(k) or HomeStyle Renovation
Both can combine a home purchase or refinance with improvement costs, but they are different programs with different requirements. We help you compare the structure, the scope each allows, and which one fits your project.
FHA 203(k)
- Government-insured renovation program through the Federal Housing Administration
- Has its own property, borrower, and project guidelines
- Commonly used for eligible structural, mechanical, and health-and-safety repairs
- Funds are disbursed as work is completed and inspected
HomeStyle Renovation
- Conventional renovation program with its own requirements
- Has its own property, borrower, and project guidelines that differ from FHA 203(k)
- May allow a range of eligible improvements, including some cosmetic work, subject to program rules
- Funds are disbursed as work is completed and inspected
How a Renovation Loan Comes Together
Renovation financing combines a home and its improvements into one transaction. Here is how the pieces generally fit, from scoping the project to disbursing improvement funds.
1. Scope the project
We talk through the home and the improvements you want to make, and you begin gathering contractor bids and a project plan.
2. Confirm program availability
We confirm whether a renovation program is currently available and review what it requires for the property, the project, and the borrower.
3. Base value plus improvement costs
Eligible renovation programs generally finance the home's value plus the cost of approved improvements, based on the expected value after the work is completed.
4. Draws as work is completed
Improvement funds are typically released in draws as work is finished and inspected, rather than in a single payment at closing.
Program confirmation and availability
Renovation loan availability, including FHA 203(k) and HomeStyle, is subject to current Coast2Coast approval, investor availability, and program eligibility. Before any application, we confirm whether a renovation program is currently available and whether your project may qualify under its requirements.
Who a Renovation Loan Is For
Renovation financing is built for borrowers who want to combine a home and its improvements into one transaction. Here is who these programs fit best.
Buyers purchasing a home that needs work
If you found a home that is livable but needs updates, repairs, or modifications, a renovation loan may let you finance the home and the improvements together.
Homeowners refinancing to improve
If you already own a home and want to finance improvements through a refinance, an eligible renovation refinance program may be worth exploring.
Borrowers comparing renovation programs
If you want to understand how FHA 203(k) and HomeStyle differ before choosing, the education-first approach here is built for you.
Borrowers seeking education before commitment
If you want to understand contractor requirements, inspection steps, and draw schedules before making financial decisions, our guidance comes with no pressure.
Questions Borrowers Bring to a Renovation Loan
Combining a home and its improvements into one loan comes with specific steps. You deserve clear guidance on program scope, contractor requirements, and how funds are disbursed before making commitments.
- Understanding whether a renovation loan fits a home that needs work
- Knowing how purchase and improvement costs combine into one financing structure
- Comparing FHA 203(k) against HomeStyle and other available renovation programs
- Understanding contractor, plan, and inspection requirements that vary by program
- Seeing how improvement funds are disbursed as work is completed
- Getting a clear, no-pressure scenario review before deciding whether to apply
How Victor Approaches a Renovation Loan
With more than 30 years of mortgage industry experience, Victor starts with your project goals and the property, not an application. Through Coast2Coast Mortgage, he checks program availability and explains how each renovation program handles improvements so you enter the project with clarity.
Share Your Project
We talk through the home you are buying or own, the improvements you want to make, and a rough sense of the project scope and budget.
Review Program Availability
We confirm whether a renovation financing program is currently available and what it requires for eligible properties and projects.
Compare Available Options
Through Coast2Coast Mortgage, I compare eligible renovation programs, including FHA 203(k) and HomeStyle where available, and explain how each handles improvements.
Move Forward With Confidence
You get a clear explanation of the structure, the contractor and inspection steps, and a recommended next step, whether that is a scenario review or more questions.
What We Compare Across Available Programs
What Clients Say
Authentic reviews are available on Victor's Google Business Profile.
Renovation Loan FAQs
Common questions about renovation financing. Program guidelines change, so treat these as educational starting points.
What is a renovation loan?
Can I finance home improvements when buying a house?
How do FHA 203(k) and HomeStyle loans differ?
Can I use a renovation loan to refinance a home I already own?
What kinds of improvements can a renovation loan cover?
Is a renovation loan currently available through The Mortgage Guide?
Related Mortgage Options
Conventional Loans
Conventional mortgage financing for eligible primary residences, second homes, and investment properties through available wholesale lending programs.
Learn moreFHA Loans
Government-insured mortgage options with flexible qualifying guidelines and low-down-payment possibilities for eligible Utah borrowers.
Learn moreVA Loans
Mortgage financing for eligible veterans, active-duty service members, and other qualifying borrowers through available VA loan programs.
Learn moreUSDA Loans
Rural development mortgage financing for qualifying buyers and eligible properties in designated Utah rural areas.
Learn moreJumbo Loans
Financing for higher-priced Utah properties requiring loan amounts above applicable conforming loan limits, through available wholesale lending programs.
Learn moreFirst-Time Homebuyer Loans
Guidance comparing financing options, qualification requirements, and the homebuying process for eligible first-time buyers in Utah.
Learn moreDown Payment Assistance
Guidance on eligible Utah down payment and closing-cost assistance programs, subject to current eligibility, funding, and participating-lender requirements.
Learn moreRate-and-Term Refinance
Refinancing to change your mortgage rate, term, or loan structure based on your individual financial goals, through available wholesale lending programs.
Learn moreCash-Out Refinance
Evaluate accessing eligible home equity through a refinance that replaces your existing mortgage with a larger loan, through available wholesale lending programs.
Learn moreHELOC and Home Equity Loans
Explore second mortgages, fixed home equity loans, and revolving home equity lines of credit that keep your existing first mortgage in place, through available wholesale lending programs.
Learn moreReverse Mortgages
Financing options for eligible older homeowners that access home equity with repayment terms and borrower obligations that differ from traditional mortgages, subject to program requirements and confirmed lender availability.
Learn moreSelf-Employed & Bank Statement Loans
Alternative-documentation mortgage financing for eligible self-employed borrowers and business owners, through available wholesale lending programs.
Learn moreInvestment Property (DSCR) Loans
Investment property financing for eligible rental property investors, including programs that may use property cash flow in qualification, through available wholesale lending programs.
Learn moreConstruction Loans
Financing options for eligible new-home construction projects, including construction-to-permanent and separate permanent financing, subject to program requirements and confirmed lender availability.
Learn moreMortgage Pre-Approval
A review of borrower qualifications, purchase budget, financing options, and documentation requirements completed before home shopping so you can act with confidence.
Learn moreBuying a Home That Needs Work in Utah?
Whether a renovation loan fits your project depends on the home, the improvements, and current program availability. Start a no-obligation conversation with Victor to understand the path that makes sense for you.