Mortgage Loans in Sandy, Utah
Reviewed by Victor Emmel, NMLS #133605. Last reviewed November 2026.
Purchase, refinance, and equity guidance for Sandy move-up families, downsizers, and buyers updating an older home. Compare loan programs and understand your next step before you apply.
Mortgage Guidance in Sandy
I help Sandy move-up families, downsizers, and buyers updating an older home compare loan programs and understand the numbers before they apply. The easiest way to start is a short conversation about your goals, your budget, and the property you have in mind. I live in Riverton in the South Valley, a short drive from Sandy.
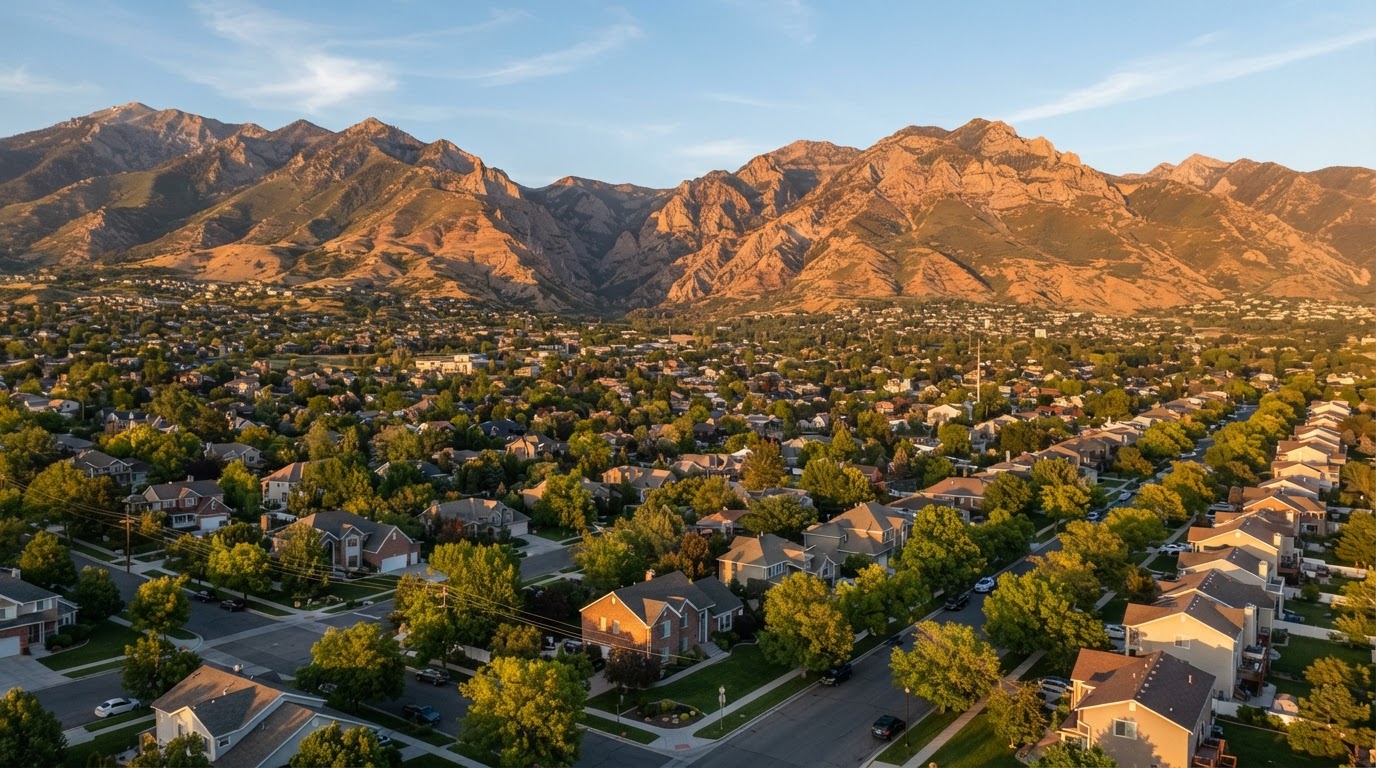
Sandy is an established city. Most single-family homes date from the 1970s through the 1990s, with larger and newer homes on the east bench toward Little Cottonwood Canyon, including Pepperwood and the Alta Canyon area. Condos and apartments cluster near the city center. Buyers ask me about the neighborhoods around Dimple Dell Regional Park and The Cairns, Sandy's city center district near America First Field and Hale Centre Theatre. The TRAX Blue Line runs through Sandy. I do not keep a walk-in office here, I meet borrowers by phone, text, email, and scheduled online meetings.
Sandy Local Image Placeholder
Loan Programs Sandy Buyers Use Most
These are the programs Sandy buyers ask me about most often, and why each one comes up in this market.
Conventional Loans
Move-up families and downsizers across Sandy's established neighborhoods compare conventional financing across wholesale lenders.
Learn moreJumbo Loans
Larger and newer homes on the east bench toward Little Cottonwood Canyon can push loan amounts above the conforming limit, where jumbo programs come into play.
Learn moreRenovation Loans
Buyers updating 1970s and 1980s homes ask me about renovation loans that fold the purchase and the improvements into one financing structure.
Learn moreHELOCs & Home Equity Loans
Long-time Sandy owners with large equity ask about HELOCs to fund goals without disturbing a first mortgage they are happy with.
Learn moreCash-Out Refinance
Owners who have held Sandy property for decades often want to compare cash-out refinance options against a HELOC to see which way of accessing equity fits.
Learn moreReverse Mortgages
Homeowners 62 and older who want to stay put ask me about reverse mortgages and how the repayment terms differ from a traditional mortgage.
Learn moreVA Loans
Eligible veterans and active-duty buyers in Sandy ask me about VA financing for purchases here.
Learn moreWhy Sandy Chooses Victor Emmel
Sandy is an established city with older homes and long-time owners who have built real equity. My guidance is built around that, not a single loan product applied to every borrower.
The Purchase Price Is Not the Whole Budget
Sandy's homes are older than those in South Jordan, Herriman, or Draper, so the purchase price is often only part of the budget. Financing the updates in the same loan is worth pricing before you make an offer, and I walk through those numbers with you up front.
Large Equity Changes the Refinance Math
Many Sandy owners have large equity and no mortgage payment to speak of, which changes the math on whether to refinance, borrow against the home, or move. I compare those options side by side so you understand which path fits your goals.
Renovation Loans for 1970s and 1980s Homes
Buyers who plan to update an older Sandy home ask me about renovation loans that fold the purchase and the improvements into one financing structure. I explain how the programs work and what documentation the project requires before you commit.
I Live in Riverton in the South Valley
I live in Riverton in the South Valley, a short drive from Sandy, and I work with Sandy borrowers by phone, text, email, and scheduled online meetings. There is no walk-in office, just direct access to me.
Sandy Mortgage FAQs
Common questions about mortgage financing in Sandy, Utah.
Do you have an office in Sandy I can visit?
I am buying a 1970s or 1980s home in Sandy and I want to update it. Can I finance the improvements?
I have owned my Sandy home for decades and have a lot of equity. Should I refinance, borrow against it, or move?
Do higher-priced east bench homes in Sandy need a jumbo loan?
I am 62 or older and I want to stay in my Sandy home. What are my options?
Which loan programs do Sandy buyers ask you about most?
Mortgage Guidance for Nearby Communities
I serve borrowers across the Salt Lake Valley. If you live in a neighboring community, the same guidance-first approach applies.
Start Your Sandy Mortgage Conversation
Tell me what you are trying to do. A short conversation can clarify which loan programs fit your Sandy property, your budget, and your goals.
Victor Emmel, NMLS #133605 · Coast2Coast Mortgage, LLC, NMLS #376205