Mortgage Loans in Draper, Utah
Reviewed by Victor Emmel, NMLS #133605. Last reviewed November 2026.
Purchase, refinance, and equity guidance for Draper move-up and executive buyers, tech-corridor professionals, and long-time owners. Compare jumbo, conventional, and self-employed programs before you apply.
Mortgage Guidance at the Point of the Mountain
I help Draper move-up and executive buyers, people working in the tech corridor between Draper and Lehi, and long-time owners using their equity compare loan programs and understand the numbers before they apply. The easiest way to start is a short conversation about your goals, your budget, and the property you have in mind. I live in neighboring Riverton, just across the Jordan River from Draper.
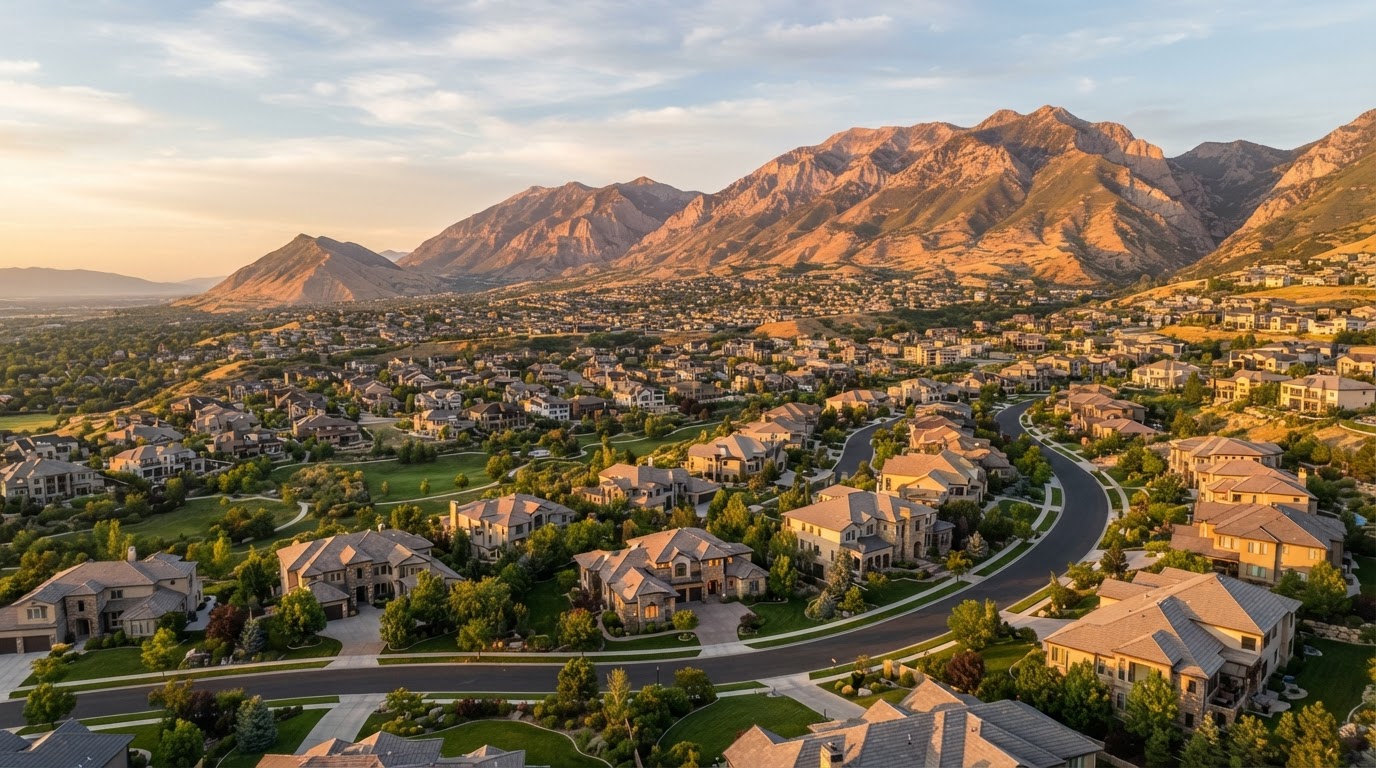
Draper is a premium market. Foothill and bench neighborhoods hold many large custom and semi-custom homes, with established family neighborhoods lower in the city and newer construction at the south end. Buyers ask me most about SunCrest on the ridge above the city, South Mountain, the Corner Canyon area and its trail system, Steeplechase, and The Point, the mixed-use redevelopment of the former state prison site at Point of the Mountain. I do not keep a walk-in office here; I meet borrowers by phone, text, email, and scheduled online meetings.
Draper Local Image Placeholder
Loan Programs Draper Buyers Use Most
These are the programs Draper buyers ask me about most often, and why each one comes up in this market.
Jumbo Loans
Many Draper prices need loan amounts above the conforming limit, so jumbo financing comes up more here than in most Salt Lake Valley cities.
Learn moreConventional Loans
Move-up and executive buyers compare conventional financing across wholesale lenders for established family neighborhoods lower in the city.
Learn moreBank Statement Loans
Self-employed buyers and business owners in the tech corridor between Draper and Lehi ask about alternative-document programs.
Learn moreHELOC & Home Equity Loans
Long-time owners using their equity ask about HELOCs to fund renovations, major expenses, or other goals while keeping their first mortgage.
Learn moreCash-Out Refinance
Owners with years of equity compare cash-out refinances against HELOCs to see which way of accessing equity fits their situation.
Learn moreVA Loans
Eligible veterans and active-duty buyers in Draper ask me about VA financing for purchases here.
Learn moreMortgage Pre-Approval
Buyers selling one home to buy another in Draper ask for pre-approval so they understand their budget before they list.
Learn moreWhy Draper Chooses Victor Emmel
Draper's premium foothill market and its spot on the county line mean borrowers here face financing questions a buyer one city over would not. My guidance is built around that.
The County Line Splits Some Addresses
Draper sits on the line between Salt Lake County and Utah County, and part of SunCrest is on the Utah County side, so county taxes and loan limits can differ by address. I check which county your property is in before we settle on a program.
High-Balance vs. Jumbo at Draper Prices
At Draper prices the choice between a high-balance conventional loan and a jumbo loan is often the main decision. I compare both side by side so you understand the credit, reserve, and down payment tradeoffs before you choose.
Bonus and Stock Income Gets Questions
Buyers paid partly in bonuses or stock should expect questions about how that income is documented. I walk through what lenders look for so you can gather the right records before we apply.
I Live Across the Jordan River in Riverton
I live in neighboring Riverton, just across the Jordan River from Draper, and I work with Draper borrowers by phone, text, email, and scheduled online meetings. There is no walk-in office, just direct access to me.
Draper Mortgage FAQs
Common questions about mortgage financing in Draper, Utah.
Do you have an office in Draper I can visit?
Part of SunCrest is in Utah County. Does that change my loan?
At Draper prices, what is the difference between a high-balance conventional loan and a jumbo loan?
I am paid partly in bonuses and stock. Can I still qualify?
Which loan programs do Draper buyers ask you about most?
I am self-employed in Draper's tech corridor. Can I qualify using bank statements?
Mortgage Guidance for Nearby Communities
I serve borrowers across the Salt Lake Valley and Northern Utah County. If you live in a neighboring community, the same guidance-first approach applies.
Start Your Draper Mortgage Conversation
Tell me what you are trying to do. A short conversation can clarify which loan programs fit your Draper property, your budget, and your goals.
Victor Emmel, NMLS #133605 · Coast2Coast Mortgage, LLC, NMLS #376205