Mortgage Loans in West Jordan, Utah
Reviewed by Victor Emmel, NMLS #133605. Last reviewed November 2026.
Purchase, refinance, and equity guidance for West Jordan buyers and homeowners. Compare FHA, conventional, VA, and equity programs before you apply.
Mortgage Guidance Across Three West Jordan Markets
I help West Jordan first-time buyers, families looking for more house for the money than the east side of the valley, and buyers of new construction compare loan programs and understand the numbers before they apply. The easiest way to start is a short conversation about your goals, your budget, and the property you have in mind. I am based two cities south in Riverton.
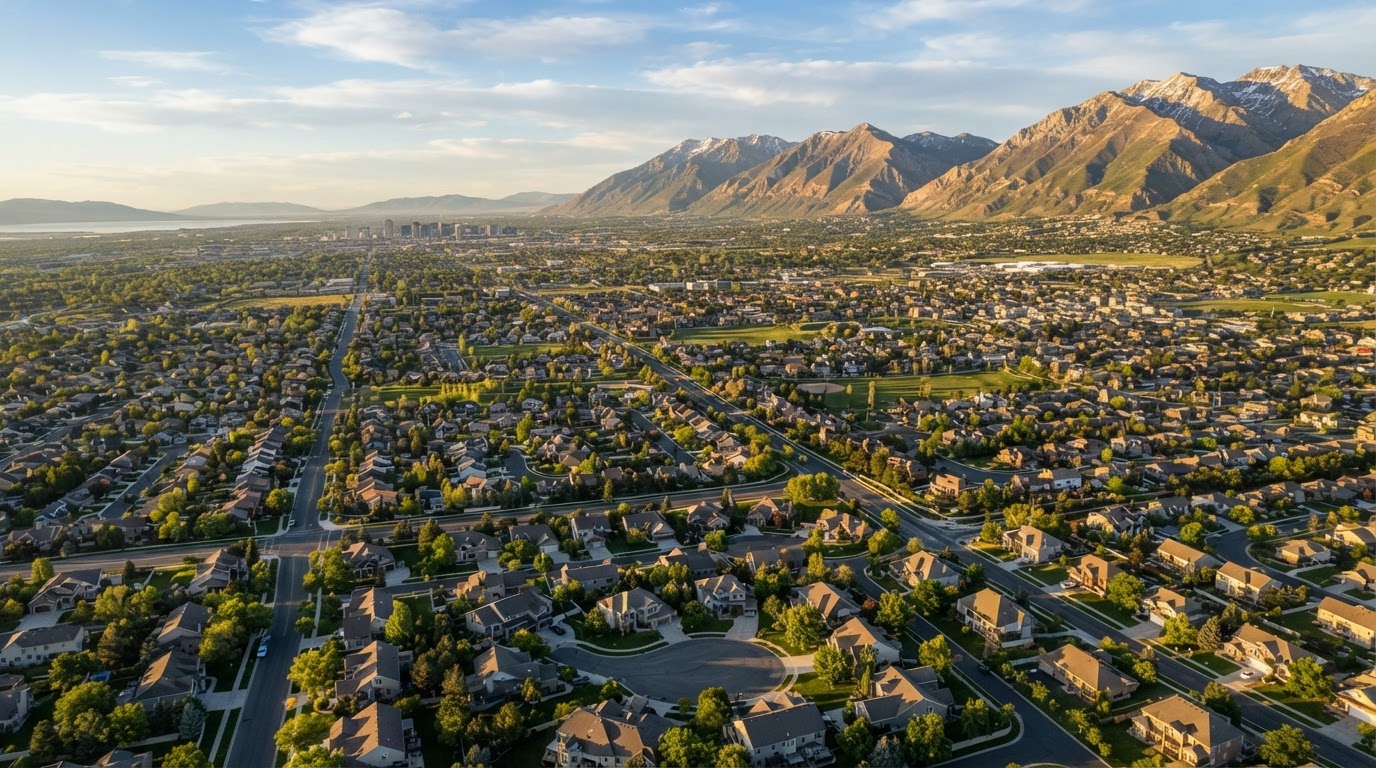
West Jordan is really three markets by age. The older central neighborhoods have 1970s ramblers, often on deeper lots with room for RV parking. Jordan Hills has 2000s family homes. And the west side along Mountain View Corridor has townhomes and single-family homes built since 2020 in newer planned communities like Terraine, Sky Ranch, Oquirrh West, and Jordan Hills, with Copper Hills nearby. Jordan Landing is the main shopping center, and Gardner Village is the historic shopping district built around an 1877 flour mill. I do not keep a walk-in office here; I meet borrowers by phone, text, email, and scheduled online meetings.
West Jordan Local Image Placeholder
Loan Programs West Jordan Buyers Use Most
These are the programs West Jordan buyers ask me about most often, and why each one comes up in this market.
FHA Loans
First-time buyers looking for more house for the money than the east side of the valley offers ask me about FHA programs and the qualifying guidelines.
Learn moreDown Payment Assistance
Eligible first-time buyers in West Jordan ask about Utah down payment assistance, subject to current eligibility and funding.
Learn moreConventional Loans
Families buying 2000s homes in Jordan Hills or move-up homes across the city compare conventional financing across wholesale lenders.
Learn moreVA Loans
Eligible veterans and active-duty buyers in West Jordan ask me about VA financing for purchases here.
Learn moreMortgage Pre-Approval
Buyers touring the newer west-side communities get pre-approval first so they understand their budget before walking the model homes.
Learn moreCash-Out Refinance
Owners of older central West Jordan homes with years of equity ask me about cash-out refinances to put that equity to work.
Learn moreHELOCs & Home Equity Loans
Long-time owners of 1970s and 2000s homes ask me about HELOCs to access equity without disturbing a first mortgage they are happy with.
Learn moreWhy West Jordan Chooses Victor Emmel
West Jordan is really three markets by age, and the financing questions change with each one. My guidance is built around knowing which market you are shopping in.
Three Markets by Age
West Jordan is really three markets by age: 1970s ramblers in the central neighborhoods, 2000s family homes in Jordan Hills, and townhomes and single-family homes built since 2020 on the west side. Knowing which of the three you are shopping in shapes the pre-approval, so I sort that out with you up front.
Older Central Homes and Repair Questions
An older central West Jordan home may need repairs that affect which loan fits and what the appraisal turns up. I walk through the condition of the home with you before you commit, so the financing matches the property.
New-Build HOA Dues and Builder Incentives
A west-side new build brings HOA dues, and those dues count toward the monthly payment a lender qualifies you on. Builders often offer incentives tied to their own lender, so it is worth comparing that offer against an outside quote before you sign. I help you price both.
I Am Based Two Cities South in Riverton
I am based in the South Valley, two cities south in Riverton, and I work with West Jordan borrowers by phone, text, email, and scheduled online meetings. There is no walk-in office, just direct access to me.
West Jordan Mortgage FAQs
Common questions about mortgage financing in West Jordan, Utah.
Do you have an office in West Jordan I can visit?
West Jordan seems to have older homes and brand-new builds. Does that change my loan?
I am looking at new construction on the west side. What should I know before I tour the models?
Which loan programs do West Jordan buyers ask you about most?
I own an older central West Jordan home with equity. Can I access it?
How do I start the mortgage conversation in West Jordan?
Mortgage Guidance for Nearby Communities
I serve borrowers across the South Valley and the Salt Lake Valley. If you live in a neighboring community, the same guidance-first approach applies.
Start Your West Jordan Mortgage Conversation
Tell me what you are trying to do. A short conversation can clarify which loan programs fit your West Jordan property, your budget, and your goals.
Victor Emmel, NMLS #133605 · Coast2Coast Mortgage, LLC, NMLS #376205